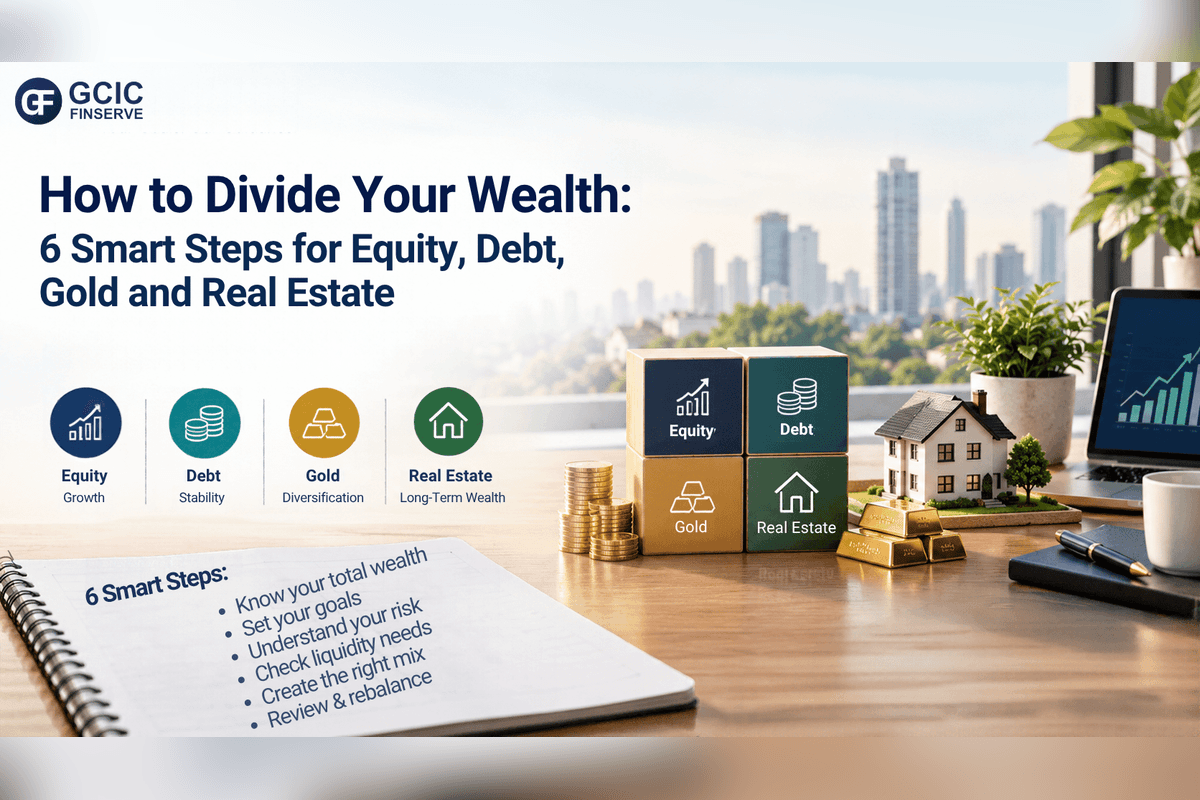
How to Divide Your Wealth: 6 Smart Steps for Equity, Debt, Gold, and Real Estate
How to divide your wealth is one of the most important financial questions a Delhi NCR family can face. Many Indian households hold a combination of property, fixed deposits, gold, mutual funds, and shares. The challenge is not simply finding investment options. It is deciding how much of your overall wealth should be allocated to each asset class.
Should you hold more equity for long-term growth? Should debt investments play a larger role in meeting financial obligations? Does every family need gold? And if you already own property, does buying another one make financial sense?
There is no universal percentage that works for everyone. The right allocation depends on your financial goals, investment horizon, income stability, liquidity requirements, risk capacity, liabilities, and existing assets.
1. The Four Asset Classes at a Glance
Each asset class can serve a different purpose in your overall financial plan.
Asset class
Potential role
Key risks
Equity
Long-term growth
Market volatility and business risk
Debt
Income and relative stability
Credit, interest-rate and inflation risk
Gold
Portfolio diversification
Price volatility and no regular income
Real estate
Property ownership and potential rental income
Illiquidity, concentration and transaction costs
The asset with the highest recent return is not necessarily the right choice for every goal. Each investment should be evaluated according to its role in your overall financial position.
2. Equity, Debt, Gold and Real Estate Explained
Equity: Equity represents ownership in businesses, either directly through shares or indirectly through equity mutual funds. It offers long-term growth potential but can experience substantial short-term declines. Money needed for emergencies or near-term expenses generally requires a different approach from money invested for long-term goals.
Debt: Debt investments involve lending money to a bank, government or company in exchange for interest and repayment according to the relevant terms. Examples include fixed deposits, government securities, corporate bonds and debt mutual funds. Their risks differ by instrument. Corporate bonds can carry credit risk, longer-duration debt can be sensitive to interest-rate changes, and inflation can reduce purchasing power.
Gold: Gold can be held as jewellery, coins, bars or through financial products such as Gold ETFs. It does not generate interest or business profits. Its price drivers can differ from those of equities and bonds, so some investors use gold as one component of a diversified portfolio rather than relying on it as the primary source of growth.
Real estate: Property can provide residential utility, potential rental income and possible appreciation. However, buying and selling property can involve substantial costs, and finding a buyer may take time. If a large proportion of your family wealth is already tied up in real estate, purchasing additional property can increase concentration risk.
3. The Biggest Mistake: Looking at Investments Separately
Imagine you have ₹50 lakh in mutual funds, ₹20 lakh in fixed deposits, ₹10 lakh in gold and ₹1.5 crore in property.
Your financial investments total ₹80 lakh, but your property exposure is much larger when viewed as part of your overall wealth.
That is why the question of how to divide your wealth should be assessed at the whole-balance-sheet level, rather than only within your mutual fund portfolio.
The same principle applies to business owners. If a substantial portion of your family's wealth depends on one operating business, your overall financial position may be more concentrated than your investment account suggests.
It is also important to account for liabilities. A family with ₹3 crore in assets and ₹1 crore in outstanding debt has a different financial position from a family with the same assets and no liabilities.
4. Start With Goals, Not Percentages
You may come across rules such as “60% equity and 40% debt” or “100 minus your age in equity.” These are simplified educational frameworks, not universal allocation rules.
Two people of the same age can have very different financial needs. One may have stable income, limited liabilities and a long investment horizon. Another may have dependants, substantial debt and a major expense approaching.
Instead of starting with “How much equity should I own?”, ask:
- When will I need this money?
- How much liquidity might I require?
- What financial losses could I realistically absorb?
- What assets and liabilities do I already have?
- Which financial goals must take priority?
An emergency fund has a different purpose from retirement savings. Money earmarked for a property purchase in three years also needs to be considered differently from money intended for a goal 15 years away.
5. The Three-Bucket Approach
A simple way to organise your financial goals is to divide money according to when it may be needed.
Bucket 1: Short-term money
This includes emergency savings, taxes and known upcoming expenses. Accessibility and capital preservation are generally important considerations. Suitable deposits and liquid investments may have a role, depending on individual circumstances.
Bucket 2: Medium-term money
This is money intended for goals expected within the next few years. Investment choices should account for the timing of the expense and the possibility of market fluctuations before the money is needed.
Bucket 3: Long-term wealth
This includes money that is not expected to be needed for many years. Depending on your goals and risk capacity, equity may play a larger role, alongside other assets where appropriate.
For illustration only, an investor with ₹1 crore in financial assets might consider a hypothetical allocation of 60% equity, 25% debt, 10% gold and 5% cash. This is an example of how different asset classes can be represented, not a recommendation or suitable allocation for every investor.
The appropriate allocation may be substantially different depending on your circumstances.
6. If You Already Own Property or a Business
Suppose your family's assets include a ₹1.5 crore home, a ₹50 lakh second property and ₹1 crore in financial investments.
Real estate represents a substantial share of the total asset value. If you have another ₹50 lakh to invest, buying another property should be considered in the context of your overall exposure, liquidity needs and financial goals.
Business owners face a similar issue. If most of their wealth is tied to their business and property, adding further investments concentrated in the same industry may increase their overall exposure to related risks.
Diversification also matters within individual asset classes. A ₹50 lakh equity portfolio spread across suitable investments is different from ₹50 lakh invested in one company's shares. Similarly, debt investments can differ significantly in credit quality, duration and liquidity.
The objective is not to own every possible asset. It is to understand where your wealth is concentrated and whether that concentration fits your financial circumstances.
7. Rebalancing and Avoiding Common Mistakes
Over time, market movements can change the proportions of your portfolio.
For example, an allocation that initially held 50% equity might move to 65% equity after a period of strong market performance. Your portfolio could then carry more equity exposure than you originally intended.
Rebalancing means bringing your portfolio closer to its intended allocation. Depending on your circumstances, this may involve directing new investments towards underrepresented assets, making withdrawals or selectively selling holdings after considering taxes and transaction costs.
Avoid these common mistakes:
- Chasing recent winners: Moving money into an asset simply because it performed well recently.
- Ignoring existing assets: Assessing mutual funds without accounting for property, business interests and other significant holdings.
- Overlooking liabilities: Making investment decisions without considering outstanding loans and future commitments.
- Holding unsuitable investments: Taking more risk than your financial goals and capacity allow.
- Reviewing too frequently: Changing your allocation in response to every short-term market movement.
Review your financial position periodically and whenever major changes occur in your income, family circumstances, liabilities or goals.
8. 6 Steps to Divide Your Wealth
Step 1: Calculate your total assets. List your financial investments, property, business interests and other significant assets. Use reasonable current estimates rather than relying only on original purchase prices.
Step 2: List your liabilities. Include outstanding loans and other significant financial commitments to understand your overall net worth.
Step 3: Separate short-, medium- and long-term goals. Identify when you expect to need each portion of your money.
Step 4: Identify concentration risks. Check whether a large share of your wealth depends on one asset class, company, sector, property or business.
Step 5: Develop a suitable allocation. Evaluate equity, debt, gold, cash and other relevant assets in light of your goals, risk capacity, liquidity needs and existing exposure.
Step 6: Review your plan periodically. Reassess your allocation as your wealth, financial responsibilities and investment goals change.
These steps provide an educational framework for organising financial decisions. They do not replace an individual assessment of investment suitability.
GCIC Finserve's Perspective for Delhi NCR Families
Families in South Delhi, Gurugram, Noida and other parts of Delhi NCR may have varied financial priorities, including retirement planning, children's education, property purchases and business expansion.
AtGCIC Finserve, investors can explore mutual fund options and learn how different investment categories may fit into their wider financial plans. The role of any distributor or financial professional should be understood according to their applicable registration and authorisation.
The decision about how much wealth to hold in property, gold or a business depends on individual circumstances. For official mutual fund category information and investor education, visitAMFI India.
Final Word
There is no universal answer to how to divide your wealth between equity, debt, gold and real estate. The more useful question is: what role should each asset play in your overall financial position?
Start with your goals, assess your assets and liabilities, understand your liquidity requirements, identify concentration risks and then evaluate an appropriate allocation.
A well-organised portfolio is not necessarily the one that owns every asset class. It is one designed around clear financial goals, realistic risk expectations and changing needs.
Frequently Asked Questions
This article is intended solely for general educational and informational purposes. It does not constitute investment, financial, tax or legal advice, or a recommendation to buy, sell or hold any security or investment product. The examples and allocations discussed are illustrative only and do not constitute investment recommendations. There is no single allocation suitable for every investor; the appropriate approach depends on individual goals, investment horizon, liquidity needs, risk capacity, liabilities and existing assets. Market-linked investments are subject to market risks, and past performance is not indicative of future results. Diversification does not guarantee returns or eliminate the risk of loss. Please review relevant scheme documents carefully before investing and consult an appropriately qualified financial professional where necessary.
Related Insights & Market Perspectives
What Happens to Your Investments After You Die? 7 Key Steps Every Delhi NCR Family Should Know
What happens to your investments after you die is a question many people avoid. We spend years deciding where to invest but very little time planning what happens to that money when we're gone. You may have mutual funds across several folios, shares in a demat account, fixed deposits with different banks, insurance policies, bonds,.
What Are Mutual Funds? A Beginner’s Guide to Smart Investing
What Are Mutual Funds? If you’re new to investing, you may have heard this question many times but still be unsure how mutual funds actually work. Mutual funds are a popular investment option because they allow investors to participate in a diversified portfolio managed by professionals. This beginner-friendly guide explains mutual fund basics, different types of.
Short-Term vs Long-Term Mutual Fund Investments: Which is Better for You?
Short term vs long term mutual funds is an important comparison for investors deciding how to align their investments with their financial goals. Mutual funds offer diversification, professional management and market-linked return potential, but the right investment approach depends on your goal, risk appetite, liquidity needs and time horizon. What Are Short-Term and Long-Term Mutual Funds?.