When Should You Exit an Investment? 6 Smart Signs Every Investor Should Watch
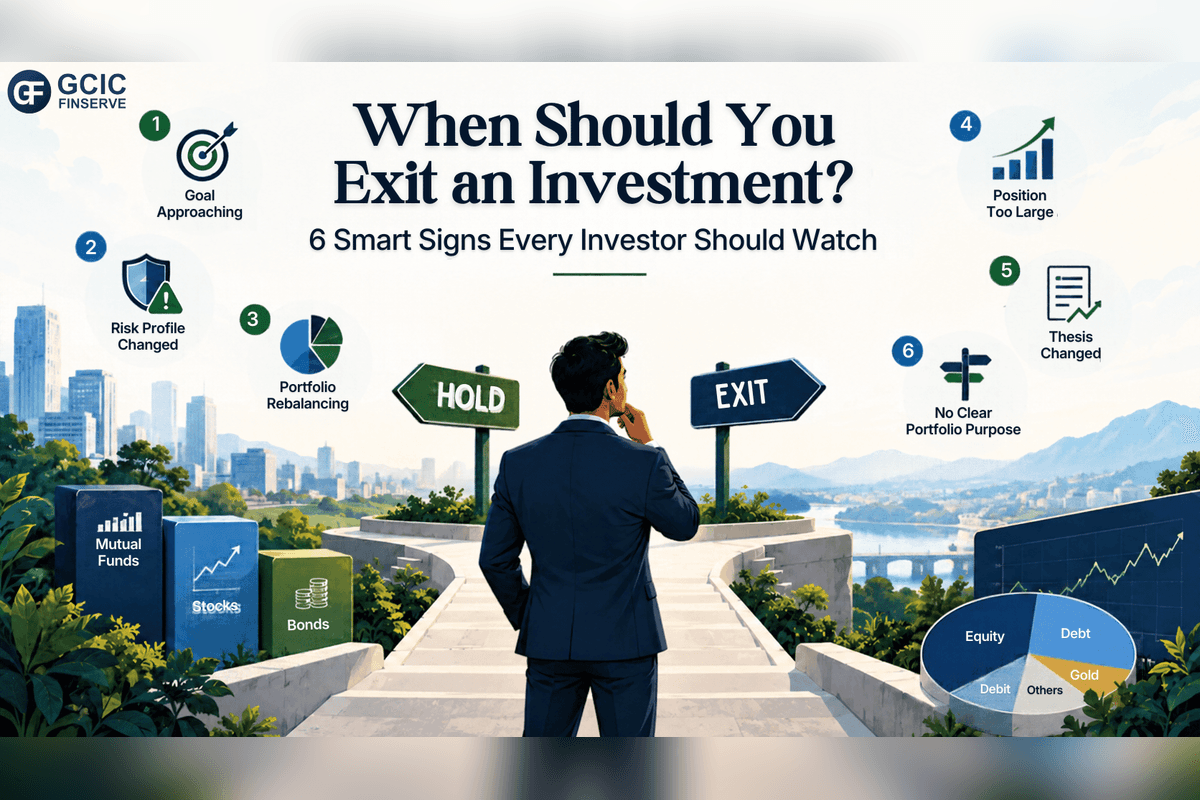
When should you exit an investment? For many investors, buying an investment feels easier than deciding when to sell it.
When an investment performs well, there may be hesitation to sell because its value could rise further. When it performs poorly, investors may continue holding it in the hope of recovering their original investment.
Both situations can lead to emotional decisions.
The right time to exit an investment does not necessarily depend on a fixed profit target or percentage loss. It depends on the original investment objective, the fundamentals of the asset, changing financial circumstances and the investment's role within a portfolio.
Understanding these factors can help investors evaluate whether an investment still serves its intended purpose.
1. Selling an Investment Isn't a Sign of Failure
Some investors associate selling with making a mistake. However, exiting an investment does not always indicate poor performance or an incorrect initial decision.
An investment may be reviewed for several reasons:
- The original investment objective has changed.
- The investor's financial goals are approaching.
- The investment represents a disproportionately large share of the portfolio.
- The investor's risk tolerance or financial circumstances have changed.
- The portfolio requires rebalancing.
- The investment no longer serves its intended purpose.
For example, an investor who initially invested in an equity mutual fund for long-term growth may eventually need to reconsider the associated market risk as the financial goal approaches.
This does not necessarily mean the investment performed poorly.
It may simply indicate that the investor's financial requirements have evolved.
Key takeaway: Selling is a portfolio decision, not necessarily a judgment about whether an investment was good or bad.
2. The First Question: Why Did You Invest?
Before deciding when to exit an investment, it is useful to revisit the reason behind the original investment.
Consider an investor who selected an equity mutual fund with a 15-year investment horizon.
After three years, the fund experiences a period of relatively weak performance.
Does this automatically justify exiting?
Not necessarily.
Short-term underperformance alone may not invalidate the original long-term investment objective.
However, if the fund experiences a material change in its stated investment approach, risk characteristics or underlying strategy, the investor may have a stronger reason to review its suitability.
A similar principle applies to individual stocks and bonds, although the factors used to evaluate them will differ.
The central question is:
Is the original reason for holding this investment still valid?
If the answer is uncertain, it may be appropriate to examine the investment's current characteristics, relevant risks and suitability rather than relying only on historical returns.
3. Six Signs It May Be Time to Exit an Investment
There is no universal rule that determines the correct exit point for every investment. However, the following six situations may justify a closer review.
Sign 1: The Original Investment Thesis Has Changed
Every investment begins with a rationale.
For an individual stock, this may involve expectations regarding business growth, profitability, competitive position, financial stability or management quality.
For a mutual fund, the rationale may involve its investment objective, category, strategy, risk profile and suitability for a particular goal.
Over time, these characteristics can change.
For example, a business may experience a sustained deterioration in its operating performance, while a mutual fund may undergo a material change in its investment approach.
Such developments may justify reassessing the original rationale.
It is important to distinguish between temporary market-related fluctuations and more fundamental changes.
Investor consideration: Has something materially changed about the investment itself, or is the concern mainly related to recent market movements?
Sign 2: Your Financial Goal Is Approaching
An investment's suitability can change as the time available to achieve a financial goal becomes shorter.
Suppose an investor has accumulated ₹20 lakh towards a child's higher education, with the expense expected in approximately eight years.
At the beginning, the investor may have been comfortable with exposure to market-linked investments.
As the education expense approaches, preserving the required funds may become increasingly important.
This can create a need to review the investment's risk exposure and liquidity.
The timing of any change depends on the investor's circumstances, goal amount, available alternatives and tolerance for potential losses.
Investor consideration: Does the investment's present risk level remain appropriate for the time left before the goal?
Sign 3: One Investment Has Become Too Large
A successful investment can gradually become a significant source of concentration risk.
Consider the following illustrative example.
An investor initially holds a portfolio worth ₹50 lakh:
- ₹5 lakh in shares of one company
- ₹45 lakh in other investments
The individual stock initially represents 10% of the portfolio.
Now suppose the value of that stock increases to ₹20 lakh while the other investments remain worth ₹45 lakh.
The portfolio is now worth ₹65 lakh, and the individual stock represents approximately 30.8% of its total value.
Although the investment has appreciated, its contribution to overall portfolio risk has increased considerably.
A high concentration in one security can expose the portfolio to company-specific developments.
This may be a reason to evaluate whether the allocation remains suitable.
Investor consideration: Has the investment grown to a level that creates more concentration risk than originally intended?
Sign 4: Your Risk Profile Has Changed
Financial circumstances are not static.
Changes in employment, family responsibilities, income stability, business commitments or retirement plans can affect an investor's ability and willingness to take financial risks.
For example, an investor with a stable salary and a long investment horizon may have a different capacity to tolerate market fluctuations than someone approaching retirement and relying on accumulated savings.
Likewise, a new financial obligation may alter liquidity requirements.
These changes do not automatically require selling existing investments.
However, they can justify reassessing whether the investment's characteristics remain appropriate.
Investor consideration: Is the level of risk associated with this investment still consistent with current financial circumstances?
Sign 5: Your Portfolio Needs Rebalancing
Portfolio allocations can change as different asset classes experience different returns.
Consider an investor who originally maintains the following allocation:
| Asset class | Original allocation |
|---|---|
| Equity | 60% |
| Debt | 30% |
| Gold | 10% |
Following a period of stronger equity performance, the portfolio may shift to:
| Asset class | Changed allocation |
|---|---|
| Equity | 72% |
| Debt | 21% |
| Gold | 7% |
The investor now has greater equity exposure than originally intended.
This is commonly known as asset allocation drift.
Rebalancing involves reviewing and adjusting the portfolio to restore an appropriate allocation.
This may involve reducing exposure to an asset class that has grown disproportionately, increasing exposure elsewhere or making adjustments through future contributions.
Rebalancing is not necessarily an attempt to predict market movements.
Its purpose is to maintain a risk structure consistent with the investor's objectives.
Investor consideration: Does the portfolio's current asset allocation still reflect its intended risk exposure?
Sign 6: The Investment No Longer Serves a Clear Portfolio Purpose
Over time, investors may accumulate several investments with similar characteristics.
For instance, multiple equity mutual funds may have substantial exposure to overlapping securities, sectors or investment styles.
Although the number of funds has increased, the underlying diversification may not have improved to the same extent.
This can make the portfolio more difficult to understand and monitor.
Reviewing portfolio overlap and the role of each holding can help identify unnecessary duplication.
However, similarity alone does not always mean a holding should be exited. Investment objectives, costs, tax implications and suitability should also be considered.
Investor consideration: Does this investment provide a distinct and useful function within the overall portfolio?
4. Why Market Movements Alone Shouldn't Determine an Exit
One of the most common investment mistakes is making decisions based solely on recent price movements.
When an Investment Falls in Value
A decline in market value does not automatically indicate that an investment has become unsuitable.
For example, an equity mutual fund may decline during a broader market correction even though its investment objective and underlying strategy remain unchanged.
A meaningful review considers the reasons for the decline.
Was the fall caused by broader market conditions, sector-specific developments, changes in the underlying holdings or deterioration in fundamentals?
Different causes may have different implications.
Equally, holding an investment merely because it has fallen is not always appropriate.
The original investment rationale and current risk must still be evaluated.
When an Investment Rises Sharply
A substantial gain does not automatically mean an investor must sell.
Suppose an investment doubles in value.
The increase may reflect strong fundamentals, favourable market conditions or changes in valuation.
Rather than looking only at the percentage gain, it may be useful to consider whether the investment still fits the investor's objectives and risk tolerance.
A helpful question is:
If I were evaluating this investment today, would its current characteristics and risks still align with my objectives?
This question encourages evaluation of present circumstances instead of relying on the original purchase price.
5. When to Exit Mutual Funds, Stocks or Bonds
Different types of investments require different considerations when evaluating an exit.
When to Consider Exiting a Mutual Fund
A mutual fund holding may deserve review when:
- Its investment objective or strategy changes materially.
- Its risk characteristics no longer suit the investor's needs.
- It experiences persistent and meaningful underperformance relative to an appropriate benchmark and comparable funds.
- Its holdings significantly overlap with other portfolio investments.
- The investor's financial goals or investment horizon change.
- The fund no longer performs a useful role in the mutual fund portfolio.
A single weak year or temporary decline in NAV is not necessarily sufficient evidence that a fund should be redeemed.
Performance assessment should consider relevant time periods, category characteristics, risk measures and market conditions.
When to Consider Exiting a Stock
Individual stocks involve company-specific risks.
Factors that may justify reviewing a stock include:
- Sustained deterioration in business fundamentals
- Weakening profitability or financial stability
- Significant increases in debt
- Corporate governance concerns
- Changes in competitive position
- Valuations that appear difficult to justify
- Excessive concentration in a single company
A declining share price may prompt further investigation, but price movement alone does not explain the underlying business condition.
When to Consider Exiting a Bond
Bonds have different characteristics from equity investments.
Some investors may intend to hold a bond until maturity, subject to the issuer meeting its obligations.
However, an earlier exit may be considered when:
- The investor's liquidity needs change.
- The issuer's creditworthiness deteriorates.
- The bond no longer matches the intended investment horizon.
- Portfolio rebalancing becomes necessary.
- Interest-rate movements affect market value and the investor's circumstances.
Investors should also understand that selling a bond before maturity may result in a price different from its face value.
Important: These are general educational considerations, not recommendations to buy, hold or sell any particular security or scheme.
6. Taxes, Exit Loads and Reinvestment Decisions
An investment exit can have financial implications beyond the difference between the purchase price and selling price.
Before selling or redeeming an investment, investors may need to evaluate the applicable taxes, transaction charges and other costs.
Capital Gains Tax
Capital gains tax treatment in India can vary depending on:
- The type of asset
- The applicable holding period
- The nature of the capital gain
- Relevant exemptions and conditions
- Tax provisions in force at the time of sale
Equity mutual funds, certain debt-oriented mutual funds, stocks and bonds may be subject to different tax rules.
Tax treatment should therefore be verified using the applicable provisions at the time of the transaction.
Mutual Fund Exit Loads
Some mutual fund schemes may charge an exit load when units are redeemed within a specified period.
The applicable conditions vary across schemes.
Investors can refer to the Scheme Information Document and other official scheme disclosures to understand these costs.
What Happens After You Sell?
Selling is only one part of the investment decision.
The next question is what happens to the proceeds.
Depending on the investor's circumstances, the funds may be required for an upcoming expense, retained for liquidity or considered for other suitable investment options.
Without understanding the purpose of the proceeds, selling may simply create another decision.
Investor consideration: What is the purpose of the funds after the exit, and how do taxes, costs and liquidity affect that decision?
7. A Simple Investment Exit Framework
Instead of making an immediate decision based on market movements, investors can use a structured set of questions to review their holdings.
Six questions to consider:
- 1Why was the investment originally selected?
- 2Is the original investment rationale still valid?
- 3Have the investor's financial circumstances or goals changed?
- 4Has the investment become disproportionately large?
- 5Does the investment still serve a useful portfolio purpose?
- 6What would happen to the proceeds if the investment were sold?
These questions do not produce an automatic buy, hold or sell decision. They provide a framework for understanding the relevant considerations.
Example: Understanding Portfolio Drift
Consider an investor with an initial portfolio worth ₹1 crore.
| Asset class | Initial value | Initial allocation |
|---|---|---|
| Equity | ₹60 lakh | 60% |
| Debt | ₹30 lakh | 30% |
| Gold | ₹10 lakh | 10% |
| Total | ₹100 lakh | 100% |
Now assume equity holdings appreciate to ₹90 lakh, while debt and gold investments remain unchanged.
| Asset class | Updated value | Updated allocation |
|---|---|---|
| Equity | ₹90 lakh | 69.2% |
| Debt | ₹30 lakh | 23.1% |
| Gold | ₹10 lakh | 7.7% |
| Total | ₹130 lakh | 100% |
The equity allocation has risen from 60% to approximately 69.2%.
The investor may review whether the changed allocation continues to reflect the intended portfolio risk.
Any rebalancing decision would also need to account for applicable taxes, transaction costs, liquidity needs and suitability.
This example demonstrates that an investment review can be driven by portfolio structure rather than a prediction about future market direction.
All amounts and allocation figures are hypothetical and provided for illustration only. They do not represent actual investment performance or a recommended asset allocation.
8. What Shouldn't Automatically Trigger an Exit?
Not every market development requires immediate action.
Some situations that can create emotional pressure include:
- A short-term market correction
- One weak quarter of performance
- A temporary decline in mutual fund NAV
- A substantial unrealized profit
- A recommendation received from another person
- Frequent financial news headlines
- Short-term changes in market sentiment
These events may provide a reason to review an investment, but they are not independently sufficient to determine whether it should be sold.
A more meaningful assessment considers the investment's objective, relevant risks, underlying characteristics, and the investor's financial circumstances.
9. GCIC Finserve's Perspective for Delhi NCR Investors
GCIC Finserve Limited
AMFI-registered Mutual Fund Distributor | ARN-272705
Investors across Delhi NCR may hold mutual funds across multiple categories, investment objectives, and risk levels.
Understanding the purpose and characteristics of these holdings is an important part of informed mutual fund investing.
AtGCIC Finserve Limited, our mutual fund distribution services include helping investors understand mutual fund scheme characteristics, assessing product suitability based on investment goals and risk profiles, and assisting with mutual fund transactions and related servicing.
Mutual fund portfolio reviews may also help investors understand category exposure, investment overlap, and whether existing mutual fund holdings continue to align with their stated objectives.
Have Questions About Your Mutual Fund Investments?
Connect with GCIC Finserve for information about mutual fund schemes, their characteristics, suitability considerations, and mutual fund distribution services.
For additional investor education resources, visit AMFI India.
11. Final Thoughts
So, when should you exit an investment?
The answer depends on more than market prices.
A change in the original investment rationale, approaching financial goals, increased concentration risk or changing personal circumstances may justify an investment review.
At the same time, short-term volatility and temporary market movements do not necessarily require immediate action.
A structured approach can help investors distinguish meaningful changes from emotional reactions.
Knowing when to buy matters. Understanding when to review, hold or exit an investment is equally important.
---
Frequently Asked Questions
Disclaimer: This article is for educational and informational purposes only and does not constitute investment or financial advice. GCIC Finserve Limited is an AMFI-registered Mutual Fund Distributor (ARN-272705), not a SEBI-registered Investment Adviser. Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. Consult a qualified professional before making investment decisions.
Related Insights & Market Perspectives
How to Divide Your Wealth: 6 Smart Steps for Equity, Debt, Gold, and Real Estate
How to divide your wealth across equity, debt, gold, and real estate? Delhi NCR families learn 6 smart steps based on goals, risk and liquidity.
What Happens to Your Investments After You Die? 7 Key Steps Every Delhi NCR Family Should Know
What happens to your investments after you die is a question many people avoid. We spend years deciding where to invest but very little time planning what happens to that money when we're gone. You may have mutual funds across several folios, shares in a demat account, fixed deposits with different banks, insurance policies, bonds,.
IMF Raises India’s FY26 Growth Forecast to 6.4% Citing Lower Inflation and Strong Reforms
IMF India growth forecast for FY2025-26 has been raised to 6.4%, up from the previous estimate of 6.2% announced in April. The upward revision in the International Monetary Fund’s latest World Economic Outlook update reflects lower inflation, a more favorable external environment and continued economic reforms. The IMF has also raised its FY2026-27 GDP growth.