Daily SIP vs Monthly SIP: What Is the Difference?
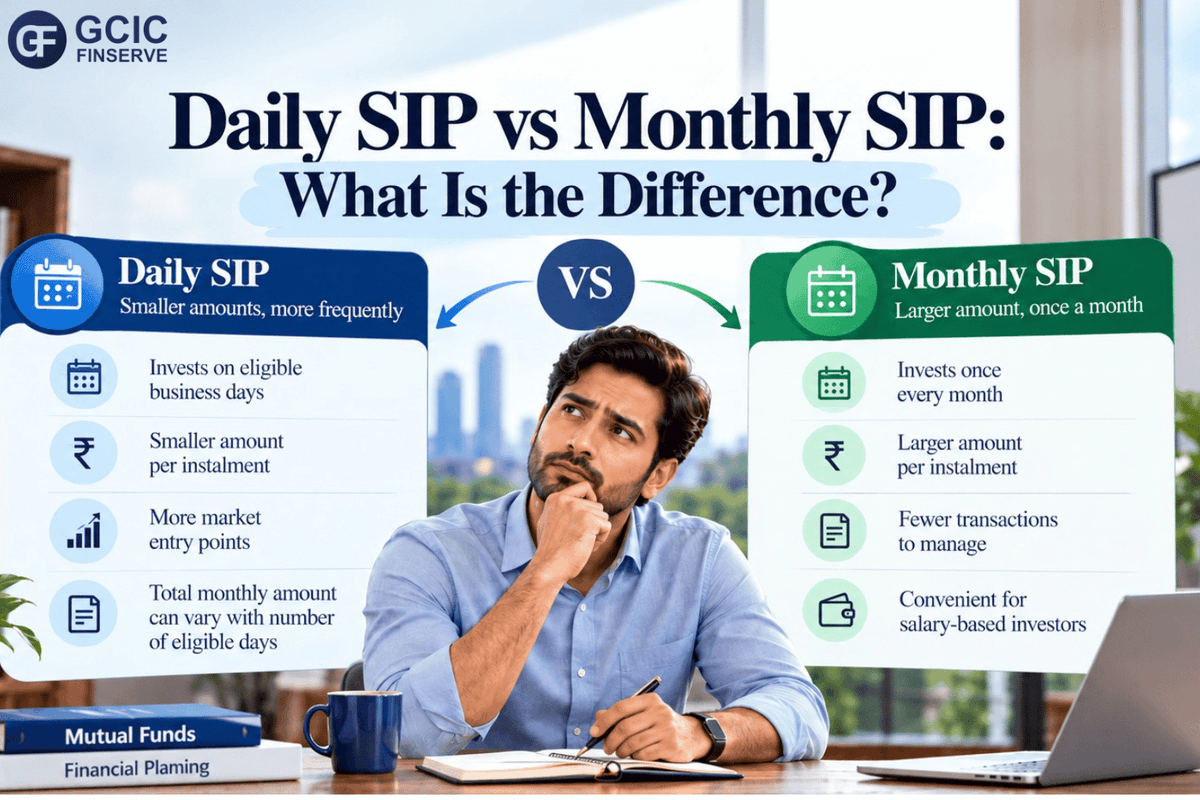
Daily SIP vs monthly SIP is a common question among investors who want to build a regular mutual fund investment habit. While some investors prefer contributing smaller amounts frequently, others find it convenient to invest once every month.
For a salaried professional in Delhi NCR, a monthly SIP may align naturally with their salary cycle. Someone with more frequent cash inflows may be interested in understanding how a daily SIP works.
But does investing more often necessarily lead to better returns?
Not necessarily.
The main difference between a daily SIP and monthly SIP is investment frequency. Both involve periodic contributions to a mutual fund scheme, but they differ in transaction schedules, cash-flow requirements, and the number of investment dates.
Neither approach guarantees superior returns.
This article explains how daily and monthly SIPs work, their practical differences, the concept of rupee cost averaging, and the important factors investors should understand before choosing a contribution frequency.
What Is a Systematic Investment Plan?
A Systematic Investment Plan, commonly known as an SIP, is a method of investing a specified amount in a mutual fund scheme at regular intervals.
Depending on the scheme's available facilities, investments may be scheduled daily, weekly, monthly, or at other permitted intervals.
An SIP is not a separate financial product. It is a method of investing in a mutual fund.
When an SIP installment is successfully processed, the investor receives mutual fund units based on the applicable Net Asset Value (NAV) and allotment rules.
NAV represents the per-unit value of a mutual fund's net assets.
As NAV changes, the number of units purchased for a fixed investment amount also changes.
For example:
- An investment of ₹1,000 at an NAV of ₹20 purchases 50 units.
- An investment of ₹1,000 at an NAV of ₹25 purchases 40 units.
These simplified calculations assume no other adjustments.
Important: The applicable NAV is determined by the relevant SEBI cut-off timing and fund-realisation rules. The scheduled SIP date does not always determine which NAV applies, and certain fund categories have different applicable NAV provisions.
SIPs can support regular investment contributions, but they do not guarantee returns or protect investors against market losses.
What Is a Daily SIP?
A daily SIP is an arrangement in which a specified amount is invested on eligible business days, according to the mutual fund scheme's terms.
Instead of investing once every month, contributions are spread across multiple dates.
How Does a Daily SIP Work?
Suppose an investor contributes ₹300 per eligible business day.
If a month has 20 eligible investment days:
₹300 × 20 = ₹6,000
If a month has 22 eligible investment days:
₹300 × 22 = ₹6,600
The actual monthly contribution depends on the number of eligible days and successful processing of the instalments.
Daily SIPs may allow investors to make smaller contributions more frequently, provided the selected scheme supports the facility.
However, minimum SIP amounts, permitted investment frequencies and processing conditions vary across mutual fund schemes.
Important Characteristics of Daily SIPs
- Contributions occur on eligible business days.
- The total monthly investment can vary with the number of eligible days.
- Units are allotted according to the applicable NAV rules.
- More frequent transactions create additional investment records.
- Sufficient funds must be available for scheduled deductions.
Key takeaway: Daily SIPs spread purchases across more dates, but that does not guarantee higher returns.
What Is a Monthly SIP?
A monthly SIP involves investing a specified amount once every month according to a selected schedule.
This frequency may be convenient for investors receiving monthly salaries or maintaining a regular household budget.
How Does a Monthly SIP Work?
Suppose an investor contributes ₹5,000 every month.
If twelve instalments are successfully processed during the year:
₹5,000 × 12 = ₹60,000
The investor receives units according to the applicable NAV and allotment rules for each investment.
The amount invested in a month generally remains fixed unless the investor modifies the SIP arrangement or a scheduled contribution fails.
Important Characteristics of Monthly SIPs
- Contributions are generally made once a month.
- The schedule may be aligned with regular income.
- Fewer transactions may simplify record-keeping.
- Units are allotted according to applicable NAV rules.
- Returns remain dependent on the underlying mutual fund.
Choosing a daily or monthly SIP does not change the underlying mutual fund's investment strategy or risk characteristics. However, differences in contribution timing and accumulated units can influence the investor's actual investment outcome.
Key takeaway: Monthly SIPs provide a structured contribution schedule, but they do not guarantee positive investment returns.
Daily SIP vs Monthly SIP: Key Differences
Both daily and monthly SIPs allow investors to make systematic contributions, but their operational characteristics differ.
| Feature | Daily SIP | Monthly SIP |
|---|---|---|
| Investment frequency | Eligible business days | Once a month |
| Contribution amount | Often smaller per instalment | Often larger per instalment |
| Market entry points | More purchase dates | Fewer purchase dates |
| Cash-flow requirements | Funds required frequently | Funds required monthly |
| Transaction records | More frequent entries | Fewer entries |
| Monthly contribution total | Can vary with eligible days | Usually fixed |
| Investment returns | Market-linked | Market-linked |
| Availability | Scheme-specific | Scheme-specific |
Investment Frequency
The most significant difference is how often investments take place.
A daily SIP spreads contributions over multiple eligible dates, whereas a monthly SIP generally processes one contribution per month.
Cash-Flow Convenience
A daily SIP requires sufficient funds for frequent deductions.
A monthly SIP may align more easily with a regular salary cycle.
The convenience of either method depends on an investor's income pattern and financial commitments.
Market Entry Points
Daily contributions generally result in purchases across more NAV dates.
Monthly contributions generally involve fewer purchase dates.
However, a greater number of purchase dates does not guarantee a lower average cost or superior investment returns.
Contribution Tracking
Daily SIPs create more investment transactions.
Monthly SIPs generally involve fewer entries, which may simplify monitoring and record-keeping.
Investment Risk
Both frequencies remain exposed to the risk characteristics of the underlying mutual fund scheme.
Changing the SIP frequency does not automatically reduce equity, credit, interest rate, or other applicable investment risks.
Does a Daily SIP Give Better Returns?
One common belief is that investing every day must generate higher returns because investments are spread across more market levels.
However, investment frequency alone does not determine returns.
A daily SIP may purchase units at several NAVs during a month.
A monthly SIP generally purchases units on one scheduled date.
Depending on market movements, one approach may accumulate more units than the other over a particular period.
This outcome can vary across different market conditions.
What Influences SIP Returns?
Investment outcomes depend on several factors:
- Performance of the underlying mutual fund
- Total contributions made
- Timing of investments
- Investment horizon
- Market volatility
- Applicable scheme expenses
When comparing daily and monthly SIPs, investors should consider similar total contributions and investment periods.
Neither frequency consistently guarantees higher returns.
Does Investing More Frequently Reduce Market Risk?
Not necessarily.
More frequent contributions can spread purchases across additional dates, but they do not eliminate the risks associated with the underlying assets.
A mutual fund investing substantially in equities remains exposed to equity-market fluctuations, regardless of whether contributions occur daily or monthly.
Key takeaway: The frequency of SIP contributions should not be mistaken for a guarantee of better returns or lower investment risk.
Understanding Rupee Cost Averaging
Rupee cost averaging is a concept associated with investing fixed amounts at different market prices.
When the NAV is lower, the same investment amount purchases more units.
When the NAV is higher, it purchases fewer units.
Example of Rupee Cost Averaging
Suppose an investor contributes ₹1,000 on three separate dates.
| Investment date | NAV | Units purchased |
|---|---|---|
| First | ₹20 | 50.00 |
| Second | ₹25 | 40.00 |
| Third | ₹16 | 62.50 |
| Total | — | 152.50 |
The total investment is ₹3,000.
The investor accumulates 152.50 units.
Average purchase cost:
₹3,000 ÷ 152.50 = approximately ₹19.67 per unit.
This illustration shows how changes in NAV affect unit accumulation.
Both daily and monthly SIPs can involve rupee cost averaging because both use periodic contributions.
However, rupee cost averaging does not assure profits, guarantee a lower purchase cost than other methods or protect against losses in declining markets.
The NAV figures and calculations above are hypothetical and do not represent any actual mutual fund scheme or investment performance.
Daily SIP and Monthly SIP: A Practical Example
Consider two hypothetical investors who intend to contribute ₹6,000 to a mutual fund over a particular month.
Investor A: Daily SIP
The investor contributes ₹300 on each eligible business day.
Assuming 20 successful installments:
₹300 × 20 = ₹6,000
The investment is spread across 20 dates.
Investor B: Monthly SIP
The investor contributes ₹6,000 once during the same month.
The investment occurs on one scheduled date.
Comparison
| Details | Daily SIP | Monthly SIP |
|---|---|---|
| Contribution per installment | ₹300 | ₹6,000 |
| Number of instalments | 20 | 1 |
| Total investment | ₹6,000 | ₹6,000 |
| Scheduled contribution dates | 20 | 1 |
Both investors contribute the same total amount in this illustration.
However, their accumulated units may differ because their contributions can be allotted at different NAVs.
The final investment value would depend on the units accumulated and the NAV at the time of valuation or redemption.
Neither method is guaranteed to produce a higher outcome.
This example assumes 20 eligible business days, successful deductions and the availability of the respective SIP facilities. Actual investment schedules and applicable NAV dates may differ.
Advantages and Limitations of Daily and Monthly SIPs
Understanding the operational advantages and limitations of each SIP frequency can help investors evaluate how these arrangements work.
Daily SIP: Potential Advantages
Frequent contributions: Investments are spread across more eligible dates.
Smaller instalments: Where permitted, the planned contribution may be divided into smaller amounts.
Multiple NAV entry points: Units may be purchased at different NAV levels during the investment period.
Daily SIP: Limitations
More transactions: Frequent contributions create more records.
Cash-flow requirements: Investors need funds available for regular deductions.
Variable monthly total: The total amount invested can vary based on eligible business days.
No assured advantage: More frequent investment does not guarantee better returns.
Monthly SIP: Potential Advantages
Convenient scheduling: Contributions may be aligned with monthly income.
Fewer transactions: A smaller number of investment entries may make record-keeping easier.
Predictable monthly contribution: The scheduled amount generally remains consistent across months.
Monthly SIP: Limitations
Fewer investment dates: Contributions are spread across fewer NAV points.
Schedule dependence: Units are allotted according to the applicable NAV for the processed transaction.
Market risk remains: Monthly investments can experience losses when underlying investments decline.
No guaranteed returns: A monthly contribution schedule does not assure a particular investment outcome.
What Should Investors Consider Before Choosing?
The choice between daily and monthly SIPs involves several practical considerations.
Income Pattern
Investors may receive income monthly, weekly or irregularly.
The frequency of available cash flows can affect the convenience of a contribution schedule.
Investment Budget
Investors should understand the total amount they intend to contribute over a particular period.
For example, ₹500 invested daily and ₹500 invested monthly involve significantly different total contributions.
Comparisons should therefore be based on similar investment amounts.
Investment Horizon
The intended investment duration is relevant to understanding the potential exposure to market movements and the suitability of the underlying mutual fund.
Risk Tolerance
An SIP frequency does not change the underlying investment objective or portfolio risk of a mutual fund.
Investors should understand the relevant scheme's investment strategy and risk characteristics.
Liquidity Requirements
Regular contributions should be assessed alongside household expenses, emergency funding needs and other financial commitments.
Scheme Availability
Not every mutual fund offers daily SIPs.
Minimum instalment amounts, investment dates and payment arrangements may differ across schemes.
Investor consideration: A contribution frequency should be evaluated in the context of the investment objective, available funds, risk tolerance, and operational convenience.
Common SIP Mistakes to Avoid
Assuming Daily SIPs Always Produce Higher Returns
More frequent investment does not guarantee superior returns.
Comparing Different Total Investments
A fair comparison should consider equivalent total contributions and investment periods.
Ignoring the Underlying Mutual Fund
The risks and potential outcomes of an SIP depend primarily on the mutual fund scheme in which money is invested.
Expecting Guaranteed Returns
SIPs are a method of investing, not a capital-protection or return-guarantee mechanism.
Overlooking Cash-Flow Requirements
A contribution schedule that does not match available funds may lead to failed instalments.
Focusing Only on Short-Term NAV Movements
Short-term fluctuations do not necessarily provide sufficient information to evaluate a longer-term investment approach.
GCIC Finserve's Perspective for Delhi NCR Investors
For investors across Delhi NCR, understanding the practical differences between daily and monthly SIPs can help clarify how systematic mutual fund investments work.
Both arrangements involve periodic contributions but differ in frequency, transaction schedules and operational convenience.
AtGCIC Finserve Limited, our mutual fund distribution services include helping investors understand mutual fund scheme characteristics, assessing product suitability based on stated investment objectives and risk profiles, and assisting with SIP registration, mutual fund transactions and related servicing.
Learn More About Mutual Fund SIPs
Connect with GCIC Finserve for information about mutual fund SIP facilities, contribution options and available mutual fund distribution services.
For official investor education resources, visitAMFI India and SEBI.
Final Thoughts
So, what is the difference between daily SIP and monthly SIP?
The main difference is how frequently money is invested.
A daily SIP spreads contributions across eligible business days, while a monthly SIP generally involves one contribution every month.
Both approaches can support systematic investing, but neither guarantees better returns.
Investors should understand their contribution budget, investment horizon, liquidity requirements, and the risks associated with the underlying mutual fund before evaluating an SIP schedule.
The frequency of investing matters less than understanding what you are investing in, why you are investing, and the risks involved.
Frequently Asked Questions
Disclaimer: This article is for general educational and informational purposes only and does not constitute personalised investment or financial advice. GCIC Finserve Limited is an AMFI-registered Mutual Fund Distributor (ARN-272705), not a SEBI-registered Investment Adviser. Mutual fund investments are subject to market risks. SIPs do not guarantee returns or protect against losses. Please read all scheme-related documents carefully before investing. Tax rules and investment conditions may change.
Related Insights & Market Perspectives
What Is GIFT City? A Simple Guide for Indian Investors (2026)
What is GIFT City and how does GIFT IFSC work? Understand its financial ecosystem, IFSCA regulation and international investment opportunities.
How to Divide Your Wealth: 6 Smart Steps for Equity, Debt, Gold, and Real Estate
How to divide your wealth across equity, debt, gold, and real estate? Delhi NCR families learn 6 smart steps based on goals, risk and liquidity.
What Happens to Your Investments After You Die? 7 Key Steps Every Delhi NCR Family Should Know
What happens to your investments after you die is a question many people avoid. We spend years deciding where to invest but very little time planning what happens to that money when we're gone. You may have mutual funds across several folios, shares in a demat account, fixed deposits with different banks, insurance policies, bonds,.