Understanding bond prices and yields can feel complicated when you first see a bond listing with terms such as 8% coupon, 7.5% yield, ₹1,000 face value, 2031 maturity, or a market price of ₹980 or ₹1,020.
But the basic idea is simple.
A bond is essentially a loan. You lend money to a government, company, or other issuer, and in return, the issuer promises to pay interest and repay the principal according to the terms of the bond.
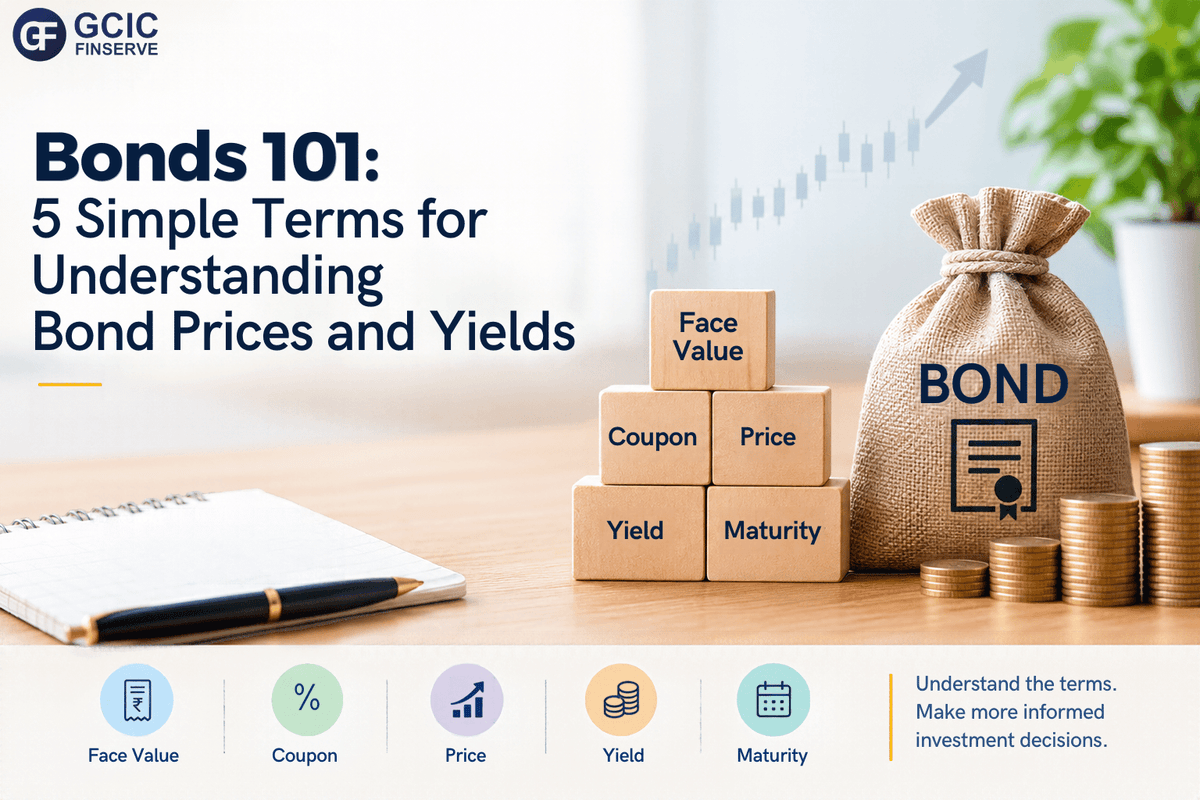
To understand most bond listings, you need to know five basic terms:
Face value, coupon, price, yield, and maturity.
Once these concepts become clear, understanding bond prices and yields becomes much easier.
A Simple Example: Lending ₹1,000
Imagine a company issues a bond with a face value of ₹1,000.
It promises to pay you 8% interest every year and repay the ₹1,000 principal after five years, subject to the issuer meeting its obligations.
This is the basic structure of a bond.
However, there is an important difference between bonds and fixed deposits: bonds can trade in the market, so their market price can move above or below their face value.
That's where understanding bond prices and yields becomes important.
- You invest: ₹1,000
- Annual coupon: 8%
- Annual interest: ₹80
- Maturity: 5 years
- Principal repayment: ₹1,000 at maturity, subject to the issuer's obligations
What Is Face Value?
Face value is the amount stated on the bond.
For example, if a bond has a face value of ₹1,000, that is the reference amount used to calculate its coupon payments. Subject to the bond's terms and the issuer meeting its obligations, the face value is normally the amount repaid when the bond matures.
However, the face value is not necessarily the price you pay.
A ₹1,000 face-value bond could trade at:
The face value remains ₹1,000, while the market price changes based on factors such as interest rates, demand, credit risk and liquidity.
- ₹1,000
- ₹1,050
What Is a Coupon?
The coupon is the interest rate specified by the bond.
The annual coupon payment would generally be:
An important point is that the coupon is calculated on the face value, not necessarily on the price you paid.
For example, if you purchase the same bond for ₹950, you would still generally receive ₹80 in annual coupon payments, subject to the bond's terms.
If you purchase it for ₹1,050, the coupon would still generally be ₹80.
So why does the market price matter?
Because your purchase price affects the yield you receive relative to your investment.
- Face value: ₹1,000
- Coupon rate: 8%
Understanding Bond Prices and Yields: Why Do Bond Prices Move?
This is one of the most important concepts for bond investors.
Bond prices and market interest rates generally move in opposite directions.
When interest rates rise
Suppose your existing bond pays an 8% coupon.
Now imagine new bonds with similar risk start offering higher rates.
Your existing 8% bond becomes relatively less attractive. Its market price may therefore fall so that its effective yield becomes more competitive.
When interest rates fall
Now imagine new bonds with similar risk offer lower rates.
Your existing 8% bond may become more attractive because it offers a higher fixed coupon than newly issued bonds.
Its market price may therefore rise.
The simple rule
When market interest rates rise, existing bond prices generally fall.
When market interest rates fall, existing bond prices generally rise.
This relationship is central to understanding bond prices and yields.
The actual price movement depends on several factors, including the bond's maturity, duration, credit quality, liquidity, and prevailing market conditions.
What Is Yield and Yield to Maturity?
The coupon rate and yield are not necessarily the same thing.
Suppose our ₹1,000 face-value bond pays ₹80 per year.
If you buy it for ₹950, your simple current yield based on the annual coupon would be:
₹80 ÷ ₹950 × 100 = 8.42%
If you buy the same bond for ₹1,050:
₹80 ÷ ₹1,050 × 100 = 7.62%
So, although the coupon remains 8%, the yield based on your purchase price changes.
What Is Yield to Maturity?
Yield to Maturity (YTM) is a more comprehensive measure.
It estimates the annualised return you may earn if you purchase the bond at its current market price and hold it until maturity, taking into account:
For example, buying a bond below its face value may result in both coupon income and a potential gain if the bond is repaid at face value at maturity, assuming the issuer meets its obligations.
This is why YTM can be more useful than coupon rate alone when comparing bonds.
However, YTM is based on assumptions and does not eliminate credit, liquidity, interest-rate, or reinvestment risks.
- Coupon payments
- Purchase price
- Time remaining until maturity
- Amount expected to be repaid at maturity
Credit Risk, Maturity, and Duration
A bond is still a form of lending, so it carries risk.
Credit Risk
Credit risk is the possibility that the issuer may not make interest or principal payments as promised.
Credit ratings such as AAA, AA, and other ratings can provide information about an issuer's creditworthiness, but a rating is not a guarantee of repayment.
A bond offering a higher yield is therefore not automatically better.
A higher yield may reflect higher perceived risk, lower liquidity, or other characteristics of the bond.
Maturity
Maturity is the date when the bond's principal is scheduled to be repaid, subject to the bond's terms and the issuer meeting its obligations.
A bond maturing in 2031, for example, has a scheduled maturity date in 2031.
Generally, the longer you remain invested, the longer your money may be exposed to changes in interest rates and other market conditions.
Duration
Duration is a measure of a bond's sensitivity to changes in interest rates.
In general, bonds with higher duration tend to experience larger price movements when interest rates change.
This is why two bonds with similar coupons can behave very differently when market interest rates move.
Bonds vs Fixed Deposits
Bonds and fixed deposits may appear similar because both can provide interest income, but they work differently.
Neither is automatically better.
The right choice depends on factors such as your financial goals, investment horizon, liquidity needs, risk tolerance and overall portfolio.
What to Check Before Buying a Bond
Don't look only at the headline coupon rate.
Before considering a bond, review:
1. Issuer
Understand who is borrowing your money.
Look at the issuer's financial position, business profile and available disclosures.
2. Credit Rating
Check the bond's credit rating and understand what it indicates about credit risk.
Remember that ratings are opinions about creditworthiness, not guarantees.
3. Coupon
Understand how much interest the bond is scheduled to pay and how frequently payments are made.
4. Market Price
Check the actual price at which you would be purchasing the bond.
A bond with a high coupon may not necessarily provide a high effective return if it is trading at a significant premium.
5. Yield or YTM
Compare the yield or YTM rather than looking only at the coupon rate.
6. Maturity
Check how long your money may remain invested and when principal is scheduled to be repaid.
7. Liquidity
Check how actively the bond trades.
A bond may be difficult to sell quickly at a desirable price if there is limited market liquidity.
8. Risks and Terms
Read the bond's documentation carefully, including applicable risks, payment terms, security, covenants and other conditions.
For official information on government securities and retail participation, investors can refer to RBI Retail Direct.
Understanding Bonds with GCIC Finserve
At GCIC Finserve, we believe investment decisions should begin with understanding the product, its risks, and how it fits into your overall financial goals.
For Delhi NCR investors, understanding the differences between bonds, fixed deposits, mutual funds, and other investment products can help create a more informed approach to financial planning.
If you want to understand how different investment options may fit your financial objectives and risk profile, connect with GCIC Finserve to discuss your requirements.
Q1. Is an 8% coupon the same as an 8% return?
An 8% coupon generally means the bond pays 8% of its face value as interest, subject to the bond's terms. Your actual return can differ depending on the price you paid, coupon payments, holding period and the amount received at maturity or sale.
Q2. Why can a ₹1,000 bond trade at ₹950?
Because bonds trade in the market.
Changes in interest rates, demand and supply, credit risk, liquidity and other market factors can cause a bond's market price to move above or below its ₹1,000 face value.
Q3. Why do bond prices fall when interest rates rise?
When new bonds offer higher interest rates, older bonds with lower fixed coupons may become less attractive.
Their market prices may therefore fall to make their effective yields more competitive.
Q4. Is a higher bond yield always better?
A higher yield may come with higher credit risk, interest-rate risk, liquidity risk, or other risks.
Investors should consider risk and return together, rather than choosing a bond only because its yield is higher.
Q5. Can I lose money in a bond?
You may experience a loss if you sell the bond at a lower market price than your purchase price.
There is also the possibility of loss if the issuer fails to meet its payment obligations.
Therefore, bonds should not automatically be considered risk-free investments.
Q6. What is the difference between a coupon and YTM?
The coupon is the interest rate specified by the bond and is generally calculated on its face value.
YTM estimates the annualised return based on the bond's current purchase price, coupon payments, time to maturity, and repayment amount at maturity, subject to its assumptions.
Q7. Are bonds suitable for every investor?
The suitability of a bond depends on factors such as your financial goals, investment horizon, liquidity requirements, and risk profile.
It is important to understand the specific bond and its risks before investing.
Final Word
Understanding bond prices and yields becomes much easier once you remember five basic concepts:
The most important relationship to remember is:
Interest rates rise → existing bond prices generally fall
Interest rates fall → existing bond prices generally rise
Once you understand this relationship, along with credit risk, maturity, duration, and YTM, bond listings become much easier to evaluate.
The goal should not be to simply find the bond offering the highest rate. Instead, consider return, risk, liquidity, maturity, and how the investment fits into your overall financial plan.
- Face Value — the amount stated on the bond
- Coupon — the interest specified by the bond
- Price — what you actually pay or receive when trading the bond
- Yield — the return implied by the price and cash flows
- Maturity — when the principal is scheduled to be repaid
Mutual fund investments are subject to market risks, read all scheme related documents carefully. Past performance does not guarantee future returns.
Related Insights & Market Perspectives
What Happens to Your Investments After You Die? 7 Key Steps Every Delhi NCR Family Should Know
What happens to your investments after you die is a question many people avoid. We spend years deciding where to invest but very little time planning what happens to that money when we're gone. You may have mutual funds across several folios, shares in a demat account, fixed deposits with different banks, insurance policies, bonds,.
Indian Hotels profit up by 232% for Q2, reaching ₹554 crore, with revenue rising by 27%.
Indian Hotels profit jumped 232% year-on-year to ₹554.6 crore in the quarter ended September 2024, compared with ₹167 crore in the same quarter of the previous fiscal year. The strong increase in quarterly profit was accompanied by a 27.4% rise in operating revenue, highlighting continued growth in the company’s hospitality business. Indian Hotels Profit Rises.
Rupee Drops as Trump Threatens Higher Tariffs on India Over Russian Oil Trade
Indian rupee falls 20 paise against the U.S. dollar on August 5 as renewed trade tensions between India and the United States triggered investor concerns. The rupee opened at ₹87.85 against the dollar, compared with the previous close of ₹87.65, as markets reacted to former U.S. President Donald Trump's threat of higher tariffs on Indian imports.