The Gold-Only Family Portfolio: Why Putting All Your Wealth in One Asset Can Be Risky
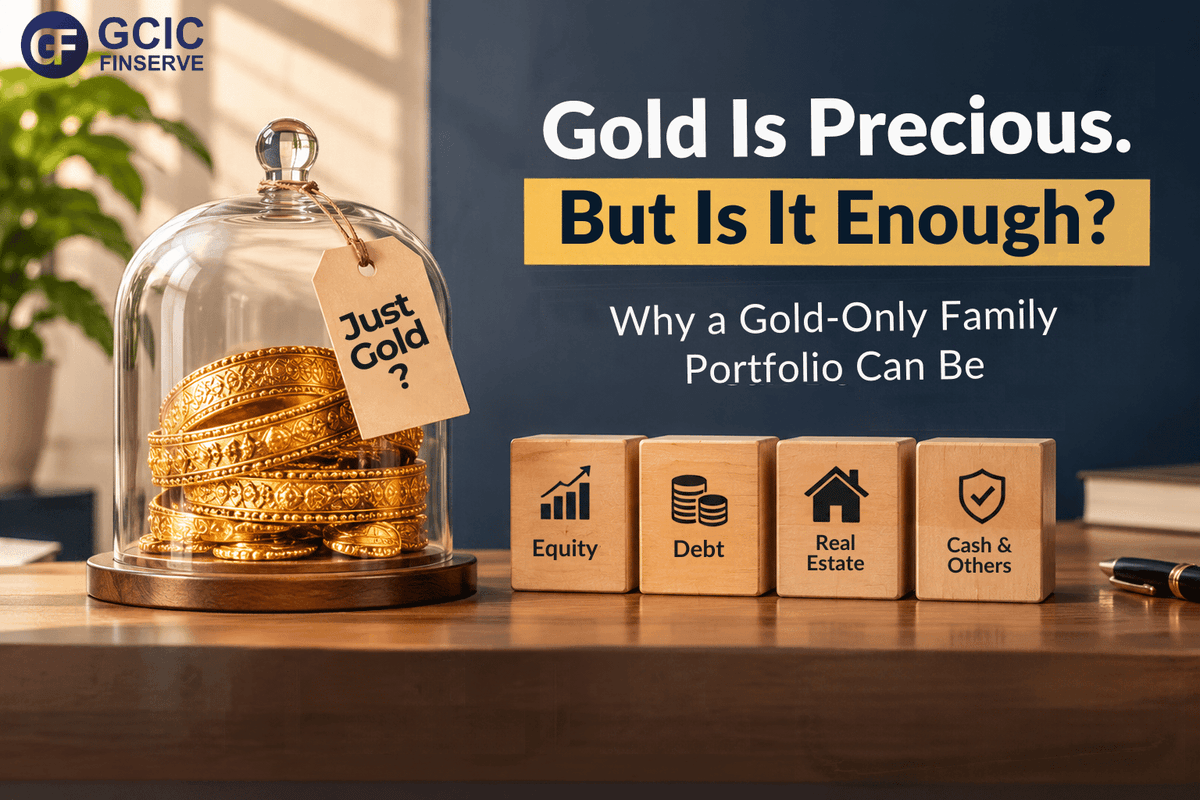
Imagine a family that has trusted gold for generations.
Their grandparents bought gold jewellery and coins. Their parents continued the tradition, purchasing more gold whenever they had surplus savings. Over time, gold became the family's preferred way of preserving wealth.
They trusted it. They understood it. And whenever someone discussed other investment options, their response was simple:
Gold has always worked for our family. Why should we invest anywhere else?
It sounds familiar, doesn't it?
But there is an important question every family should consider: Can depending on just one asset really protect wealth over the long term?
The story of a gold-only family portfolio highlights an important investment lesson: an asset can be valuable without being suitable as the only place to keep your wealth.
Why Do Indian Families Trust Gold?
Gold has a special place in Indian households. It is associated with festivals, weddings, family traditions, and financial security.
Many families buy gold because:
- It has cultural and emotional significance.
- It can be passed from one generation to another.
- It is widely recognised and traded.
- It may help preserve purchasing power over certain periods.
- It provides exposure to an asset outside traditional financial investments.
For many households, gold is more than an investment. It represents memories, security and family heritage.
There is nothing inherently wrong with owning gold. The concern begins when a family depends on it almost entirely for its financial future.
What Is the Problem With a Gold-Only Portfolio?
A portfolio is a collection of assets held to meet financial goals.
If most or all of a family's wealth is concentrated in gold, its financial position becomes heavily dependent on the performance of one asset class.
Gold prices can rise and fall due to several factors, including:
- Global economic uncertainty.
- Interest rate expectations.
- Inflation and currency movements.
- Central bank demand.
- Geopolitical developments.
- Investor sentiment.
Gold has historically played a diversification role in many portfolios, but it is not free from price volatility. Its performance can vary significantly across different periods.
A family that needs money during a period of falling gold prices may have to sell at an unfavourable time.
This is one of the risks of depending on a single asset.
Gold Does Not Generate Regular Income
Another important consideration is income.
Physical gold generally does not generate regular interest, dividends, or rental income. Its financial benefit primarily depends on changes in its market value.
For example, a family holding gold jewellery may see its market value increase over time. However, the jewellery itself does not provide regular cash flow to pay for:
- Monthly household expenses.
- Children's education.
- Medical expenses.
- Retirement requirements.
- Other planned financial commitments.
This does not mean gold has no place in a portfolio. It simply means families should understand the difference between owning an asset and holding an asset that generates regular income.
The Hidden Costs of Holding Physical Gold
Physical gold also comes with practical considerations that investors sometimes overlook.
Making charges: Jewellery purchases may include making charges. These charges can affect the overall purchase cost and may not be fully recovered when the jewellery is sold.
Purity: Buyers should check the purity and hallmark details before purchasing gold jewellery. In India, the BIS hallmark includes the BIS logo, purity mark and a six-digit alphanumeric Hallmark Unique Identification (HUID) number for applicable hallmarked articles. Consumers can verify the HUID through the BIS Care App.
Storage and security: Physical gold needs safe storage and protection against theft or loss. Secure storage may also involve additional costs.
Resale value: The amount received when selling jewellery may differ from the original purchase price. Purity, weight, applicable deductions, prevailing gold prices, and the jeweller's buyback terms can affect the final amount.
These factors matter when evaluating the actual financial value of a family's gold holdings.
Why Portfolio Diversification Matters
Diversification means spreading investments across different asset classes instead of depending on a single investment.
Different asset classes can behave differently under changing economic and market conditions. The purpose is to reduce dependence on one source of returns, although diversification cannot eliminate all investment risks.
For example:
| Asset class | Potential role in a portfolio | Important consideration |
|---|---|---|
| Gold | Diversification and potential store of value | Price volatility: physical gold has storage and transaction considerations |
| Equity | Long-term growth potential | Market risk and price fluctuations |
| Debt instruments | Interest income and portfolio diversification | Interest rate and credit risk |
| Cash and liquid assets | Meeting short-term financial needs | Inflation can reduce purchasing power |
| Real estate | Property ownership and potential rental income | Liquidity, maintenance, and market risks |
Each asset has its own advantages and risks. The right mix depends on financial goals, investment horizon, liquidity requirements, and risk tolerance.
There is no single allocation that is suitable for every family.
How Can Families Think Beyond a Gold-Only Portfolio?
Families do not need to abandon gold to think about diversification.
Instead, they can start by understanding their overall financial position.
Here are five useful questions:
1. How much of the family's total wealth is in gold?
Look beyond jewellery and consider all forms of gold ownership. Understanding concentration is the first step.
2. What are the family's upcoming financial goals?
Education, retirement, property purchases and other major expenses may require different investment horizons.
3. Is there enough money available for emergencies?
Families should consider their short-term liquidity needs rather than depending entirely on selling long-term assets.
4. Are investments spread across different asset classes?
Understanding the role of equity, debt, gold and other assets can help families evaluate their overall portfolio.
5. When was the portfolio last reviewed?
Family circumstances and financial goals change over time. A portfolio should be reviewed periodically to check whether it still reflects those requirements.
- 7The Real Lesson: Preserve Wealth Through Understanding, Not Habit
The gold-only family portfolio teaches us something important about investment behaviour.
Sometimes, families continue making financial decisions simply because previous generations followed the same approach.
Traditions can be meaningful, but financial decisions should also reflect changing goals, market conditions, and future responsibilities.
Gold can be an important part of a family's wealth. But depending entirely on one asset may expose the family to unnecessary concentration risk.
A more informed approach begins with understanding what each asset does, what risks it carries, and how it fits into the family's broader financial picture.
Final Thoughts
The Gold-Only Family Portfolio is not a story about gold being a bad investment. It is a reminder that even a familiar and valuable asset can become risky when a family depends on it too heavily.
Building and preserving family wealth requires more than following old habits. It requires understanding different asset classes, managing risk, and reviewing financial goals as life changes.
Explore ourMutual Fund Services, use ourInvestment Tools, orconnect with our team to learn more.
Useful Resources
Frequently Asked Questions
Disclaimer: This content is for educational and informational purposes only and should not be considered investment, tax or legal advice, or a recommendation to buy, sell or hold any investment. Investments are subject to market risks and possible loss of capital. Please read all relevant scheme documents carefully before investing. GCIC Finserve Limited is an AMFI-registered Mutual Fund Distributor (ARN-272705) and is not a SEBI-registered Investment Adviser.
Related Insights & Market Perspectives
Types of Mutual Funds and How to Choose the Right One for You
Understand the types of mutual funds in India, their features and risks. Learn how to choose funds based on your financial goals and investment horizon.
Daily SIP vs Monthly SIP: What Is the Difference?
Daily SIP vs monthly SIP: Understand how investment frequency, convenience, market volatility, and long-term goals differ before choosing an SIP approach.
What Is GIFT City? A Simple Guide for Indian Investors (2026)
What is GIFT City and how does GIFT IFSC work? Understand its financial ecosystem, IFSCA regulation and international investment opportunities.