Types of Mutual Funds and How to Choose the Right One for You
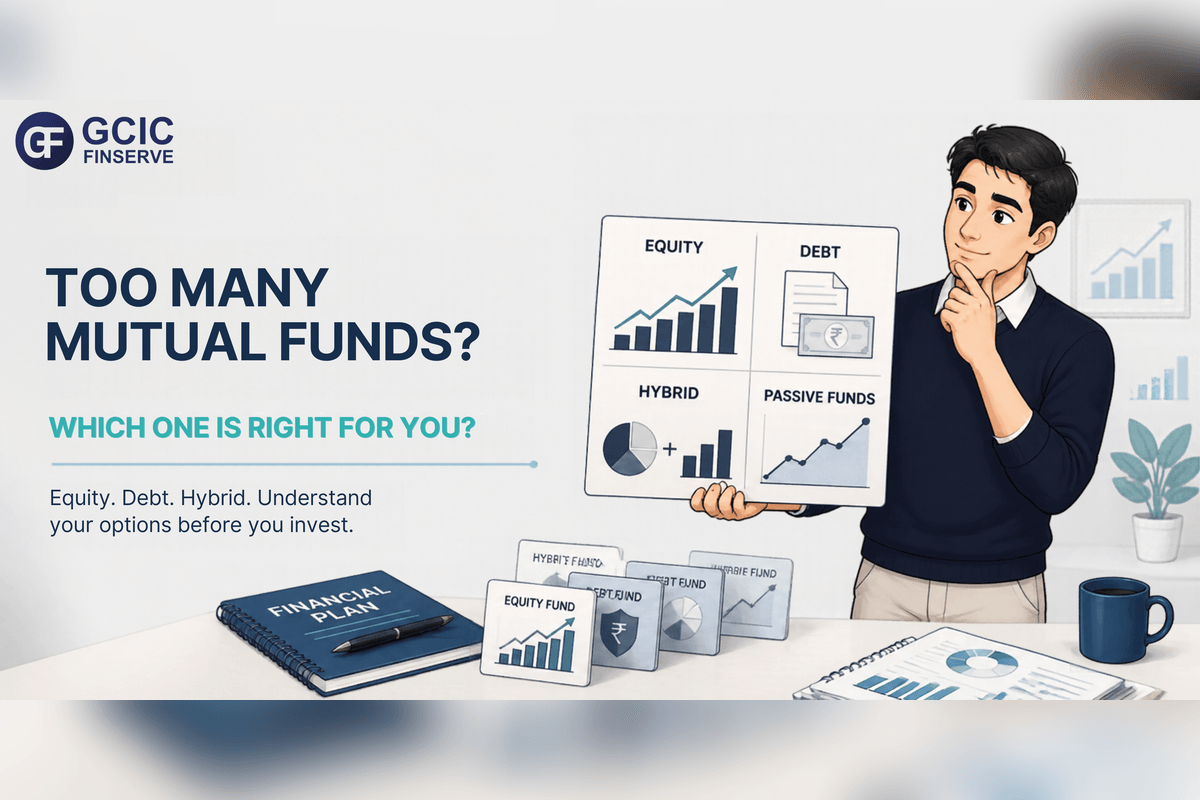
Have you ever wondered why there are so many mutual fund options available in India? From equity and debt funds to hybrid and index funds, each category serves a different investment purpose.
For someone starting their investment journey, understanding the different types of mutual funds can feel confusing. Some funds primarily invest in company shares, while others focus on debt securities or a combination of asset classes.
However, choosing a mutual fund should not simply depend on which fund delivered the highest returns last year. Your financial goals, risk appetite, and investment time horizon matter much more.
In this guide, GCIC Finserve explains the major categories of mutual funds in India and the factors to consider when evaluating a scheme.
What Are Mutual Funds?
A mutual fund is an investment vehicle that pools money from multiple investors and invests it in assets such as company shares, government securities, corporate bonds, and other permitted financial instruments.
These investments are managed by professional fund managers according to the scheme's investment objective.
When you invest in a mutual fund, you receive units based on the amount invested and the applicable Net Asset Value (NAV).
Mutual funds allow investors to access different asset classes without having to select and manage every individual security themselves.
Major Categories of Mutual Funds in India
Understanding the types of mutual funds starts with knowing how schemes are classified.
SEBI's circular dated 26 February 2026 broadly classifies mutual fund schemes into five groups: equity schemes, debt schemes, hybrid schemes, life cycle funds, and other schemes. Other schemes include fund of funds and passive schemes such as index funds and ETFs.
Let's understand what these categories mean.
1. Equity Mutual Funds
Equity mutual funds primarily invest in shares of companies listed on the stock market. Their main objective is long-term capital appreciation.
These funds are generally suitable for investors who can accept market fluctuations and have an appropriate investment horizon.
Common types of equity funds include:
- Large-Cap Funds: Invest primarily in established, large-sized companies.
- Mid-Cap Funds: Focus on medium-sized companies.
- Small-Cap Funds: Invest in smaller companies and generally carry higher volatility.
- Flexi-Cap Funds: Invest across large, mid, and small-cap companies, with flexibility in allocation.
- Sectoral and Thematic Funds: Focus on specific industries or investment themes.
- ELSS Funds: Equity-linked savings schemes that may offer tax benefits under Section 80C, subject to applicable tax rules and eligibility.
Risk level: Generally high to very high, depending on the fund category and portfolio.
2. Debt Mutual Funds
Debt mutual funds primarily invest in fixed-income instruments such as government securities, treasury bills, corporate bonds, and money market instruments.
These funds aim to generate returns through interest income and changes in the market value of debt securities.
Common types include:
- Liquid Funds: Invest in short-maturity debt and money market instruments.
- Short-Duration Funds: Invest in debt securities with a defined portfolio duration range.
- Corporate Bond Funds: Primarily invest in corporate bonds meeting specified credit-quality requirements.
- Gilt Funds: Invest predominantly in government securities.
Debt funds are not risk-free. Their value can be affected by interest rate movements, credit quality, and liquidity conditions.
Risk level: Varies from relatively low to high, depending on the portfolio.
3. Hybrid Mutual Funds
Hybrid mutual funds invest in a combination of asset classes, generally equity and debt. Depending on the scheme, they may also invest in other permitted asset classes.
The objective is to combine the growth potential of equity with the different risk and income characteristics of other assets.
Common types include:
- Aggressive Hybrid Funds: Have a relatively higher allocation to equity.
- Conservative Hybrid Funds: Primarily invest in debt, with a smaller equity allocation.
- Balanced Advantage Funds: Dynamically adjust equity and debt exposure according to the scheme's strategy.
- Multi-Asset Allocation Funds: Invest across at least three asset classes, subject to applicable scheme requirements.
- Equity Savings Funds: Combine equity, debt, and arbitrage strategies.
Hybrid funds may suit investors looking for exposure to more than one asset class through a single scheme.
Risk level: Moderate to high, depending on the asset allocation and investment strategy.
4. Life Cycle Funds
Life cycle funds are designed around a target investment horizon or life-stage objective.
Their asset allocation is structured to change over time according to the scheme's investment strategy, generally moving towards a more conservative allocation as the target date approaches.
They may be relevant for investors planning towards a future financial milestone, such as retirement.
However, their suitability depends on the investor's actual financial needs, risk tolerance and liquidity requirements.
Risk level: Depends on the fund's asset allocation and how it changes over the investment period.
5. Other Mutual Fund Schemes
SEBI's broad classification also includes Other Schemes. This group includes fund of funds and passive schemes such as index funds and exchange-traded funds (ETFs).
Let's understand these options.
Index Funds
Index funds are passive mutual funds that aim to replicate the performance of a particular market index, such as the Nifty 50 or Sensex.
Instead of actively selecting stocks to outperform the market, these funds follow the composition of their chosen benchmark.
Key features:
- Follow a specified market index.
- Generally have a passive investment approach.
- Usually involve lower portfolio-management costs than comparable active funds.
- Their performance is influenced by the underlying index and tracking difference.
Index funds may appeal to investors who prefer a market-linked, passive investment approach.
Risk level: Depends on the index being tracked.
Exchange-Traded Funds (ETFs)
ETFs are investment funds that trade on stock exchanges, similar to individual shares.
They can track equity indices, bonds, gold, or other permitted underlying assets.
Unlike conventional mutual fund transactions, ETF units are bought and sold on the stock exchange during trading hours.
Key features:
- Exchange-based buying and selling.
- Usually track an index or underlying asset.
- Require a demat and trading account for exchange transactions.
- Market price may differ from the fund's NAV.
ETFs may suit investors who prefer exchange-based investing and understand how market orders, liquidity, and bid-ask spreads work.
Fund of Funds (FoFs)
A fund of funds invests in units of other mutual fund schemes rather than directly investing primarily in individual securities.
It provides access to multiple underlying funds through a single investment.
Key features:
- Invests in one or more underlying schemes.
- Can offer exposure to different strategies or asset classes.
- May involve an additional layer of expenses.
- Its risk depends on the underlying investments.
Before investing, review the underlying schemes, total costs, and investment strategy.
Important: Index funds, ETFs, and fund of funds are discussed separately here to explain their investment approach. Under SEBI's broad classification, they fall under Other Schemes as applicable.
How to Choose the Right Mutual Fund for You?
Knowing the types of mutual funds is important, but selecting the right scheme requires more careful consideration.
Here are six practical factors to evaluate.
1. Start With Your Financial Goals
First, identify why you are investing.
Your investment objective could be:
- Building long-term wealth.
- Saving for a child's education.
- Planning for retirement.
- Creating funds for a future purchase.
- Managing surplus money.
A clear goal helps narrow down the mutual fund categories worth considering.
2. Understand Your Risk Appetite
Every investor has a different ability and willingness to handle market fluctuations.
For example, an investor comfortable with significant short-term fluctuations may consider equity-oriented schemes, while someone seeking a different risk profile may explore debt or hybrid categories.
Remember that even debt mutual funds carry risks. No mutual fund category guarantees returns or protects against every loss.
You should also check the scheme's Riskometer, which indicates the level of risk associated with the scheme. Read it along with the scheme's investment objective, portfolio and other disclosures.
3. Consider Your Investment Time Horizon
How long can you remain invested without needing the money?
Your investment horizon can influence which categories you evaluate.
- Short-term needs: Explore suitable short-duration investment options while carefully assessing liquidity and credit risk.
- Medium-term goals: Consider categories that match your required timeline and ability to absorb fluctuations.
- Long-term goals: Equity-oriented funds may be worth evaluating if you can tolerate market volatility.
These are broad considerations, not fixed rules. The right choice depends on your individual circumstances.
4. Compare the Fund's Performance and Consistency
Past performance should not be the only reason to select a mutual fund.
Instead, examine:
- Performance across different market cycles.
- Comparison with the appropriate benchmark.
- Consistency over different periods.
- Portfolio quality and investment strategy.
- Fund manager's approach and experience.
A fund that performed exceptionally well in one year may not necessarily continue to do so.
5. Check Expense Ratio and Exit Load
The expense ratio represents the annual cost of managing a mutual fund scheme and affects the investor's overall returns.
An exit load may apply when units are redeemed within a specified period.
Before investing, review these costs and understand how they apply to your investment.
6. Diversify Your Investment Portfolio
Putting all your money into one fund or investment category can increase concentration risk.
Depending on your financial goals and risk appetite, diversification across suitable asset classes and investment strategies may help manage portfolio risk.
However, owning multiple funds does not automatically mean your portfolio is diversified. Check whether their underlying investments overlap.
Common Mistakes to Avoid While Choosing Mutual Funds
Even experienced investors can make avoidable mistakes. Watch out for these common errors:
- 1Chasing last year's winners: A fund's past performance does not guarantee future returns.
- 2Ignoring risk: Higher potential returns generally involve higher investment risk.
- 3Investing without a goal: Every investment should have a clear purpose.
- 4Selecting too many funds: Multiple schemes with similar portfolios may create unnecessary overlap.
- 5Ignoring costs: Expense ratios and exit loads can affect your investment experience.
- 6Reacting emotionally to market movements: Investment decisions should be based on your goals rather than short-term market sentiment.
Final Thoughts: Choose Mutual Funds Based on Your Goals, Not Trends
There is no single mutual fund that is suitable for every investor.
Understanding the different types of mutual funds can help you evaluate investment opportunities more confidently. However, the right selection depends on your financial goals, investment horizon, risk appetite, and overall portfolio.
Instead of chasing recent returns or following market trends, take time to understand the scheme's investment objective, portfolio, costs, and associated risks.
At GCIC Finserve, we believe that informed investment decisions begin with understanding your financial needs and choosing an appropriate investment approach.
Plan your investments with clarity. Build your portfolio with purpose.
ExploreGCIC Finserve's financial tools to understand and plan different aspects of your investments. You can also explore ourmutual fund services orconnect with our team.
Useful Resources
Investors across Delhi NCR can explore the following resources:
Frequently Asked Questions
Disclaimer: Mutual Fund investments are subject to market risks; read all scheme-related documents carefully. The information provided in this article is for educational and informational purposes only and should not be considered investment advice or a recommendation to buy or sell any mutual fund scheme. Investors should assess their financial goals, risk appetite, and investment horizon before making investment decisions. GCIC Finserve Limited is an AMFI-registered Mutual Fund Distributor (ARN-272705), not a SEBI-registered Investment Adviser.
Related Insights & Market Perspectives
Daily SIP vs Monthly SIP: What Is the Difference?
Daily SIP vs monthly SIP: Understand how investment frequency, convenience, market volatility, and long-term goals differ before choosing an SIP approach.
What Is GIFT City? A Simple Guide for Indian Investors (2026)
What is GIFT City and how does GIFT IFSC work? Understand its financial ecosystem, IFSCA regulation and international investment opportunities.
How to Divide Your Wealth: 6 Smart Steps for Equity, Debt, Gold, and Real Estate
How to divide your wealth across equity, debt, gold, and real estate? Delhi NCR families learn 6 smart steps based on goals, risk and liquidity.